

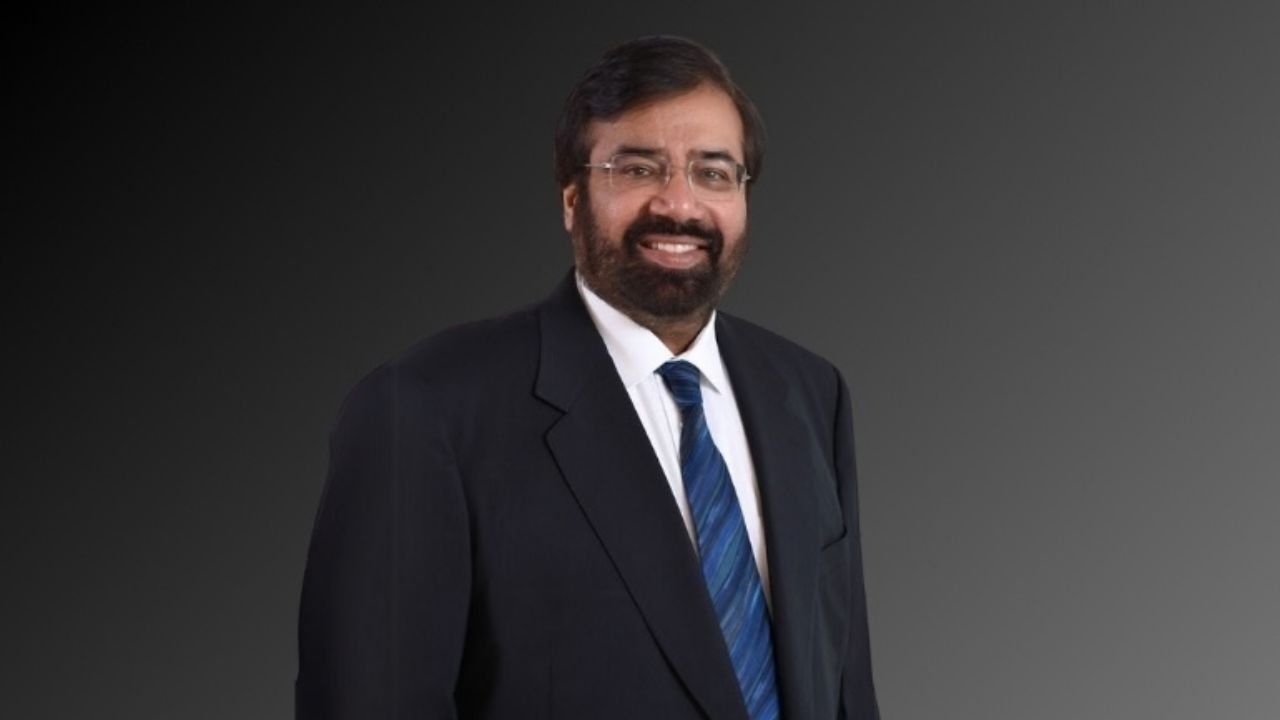
New Delhi. RPG Enterprises Chairman Harsh Goenka has called for a more favourable tax regime for scientific research in India, questioning why laboratories continue to face GST on essential equipment, software and other research inputs while cricket receives tax relief. Goenka said he welcomed support for cricket, describing it as a major Indian success story, but argued that research and development should receive comparable policy encouragement if India wants to strengthen its technological and scientific capabilities.
Goenka said the preferable approach would be to remove GST on essential research inputs, reducing the cost of conducting scientific work. His intervention has brought renewed attention to the tax treatment of laboratory equipment and research expenditure at a time when India is seeking greater domestic capability in technology, manufacturing and innovation.
Proposal for Conducting Cyber Crisis Drill, Tabletop Exercise (TTEx) & CCMP Readiness Exercise
Goenka Calls for Tax-Friendly Treatment of Research
Goenka’s argument centres on the cost of building and operating research facilities. Scientific laboratories require specialised instruments, computers, software, consumables and technical equipment, many of which fall within taxable categories under the Goods and Services Tax framework.
In his remarks, Goenka said he was happy that the BCCI received tax relief because cricket deserved encouragement, but questioned why research laboratories should continue paying GST on essential equipment and software. He argued that if sports can receive tax-friendly treatment, research and development should also be supported through a similar policy approach.
The issue is particularly relevant because specialised scientific equipment can represent a substantial part of the cost of establishing or expanding a laboratory. The GST structure currently places several categories of laboratory machinery and scientific instruments in the 18 per cent bracket. The CBIC rate schedule, for instance, lists several forms of laboratory machinery and scientific measuring or analytical instruments at an 18 per cent GST rate.
Goenka’s suggestion is therefore broader than a demand for additional research funding. His argument is that reducing taxes on the inputs needed for experimentation could allow laboratories to direct a larger share of their resources towards research itself.
The tax treatment of scientific equipment has changed significantly since the introduction of GST. In November 2017, the government introduced a concessional GST regime for specified scientific and technical equipment supplied to eligible publicly funded research institutions. The concession effectively provided a 5 per cent GST rate on qualifying supplies, including scientific and technical instruments, equipment, accessories and certain other research-related items.
Research Equipment Lost Its 5% GST Concession in 2022
The concessional arrangement was subsequently withdrawn. During the 47th GST Council process in 2022, the Group of Ministers on rate rationalisation recommended ending the reduced 5 per cent GST rate on scientific and technical instruments supplied to publicly funded research institutes.
The recommendation said the concession was creating an inverted rate structure and proposed that standard GST rates applicable to individual products should instead apply. The GST Council accepted the recommendation, and the relevant Central and Integrated GST notifications providing the concession were rescinded with effect from July 2022.
Official GST Council records subsequently acknowledged the impact of that decision. In discussions relating to scientific equipment used in the Research Moored Array for African-Asian-Australian Monsoon Analysis and Prediction programme, the Council noted that equipment which had earlier benefited from a concessional 5 per cent IGST rate was attracting 18 per cent after the broader research-institution concession was withdrawn. A special exemption was later considered for that particular international research programme.
The tax position is nevertheless more nuanced than saying that every form of research activity is taxed uniformly. The government has provided relief in other areas. From October 10, 2024, research and development services supplied by specified government entities, research associations, universities, colleges and qualifying institutions against government grants were specifically exempted from GST.
This means the present framework distinguishes between different kinds of research expenditure. Certain qualifying R&D services funded through government grants can receive an exemption, while laboratories purchasing equipment, software or other inputs may still face the applicable GST rate attached to those goods or services.
Tax policy has also historically been used to encourage scientific research through the income-tax system. The Union government’s 2026-27 Receipt Budget recorded a revenue impact of ₹3,822.94 crore in 2023-24 from deductions linked to expenditure on scientific research, with the corresponding figure projected at ₹4,319.93 crore for 2024-25.
BCCI Does Not Have a Blanket Tax Exemption
Goenka’s comparison with cricket requires an important distinction. His public comments referred to BCCI receiving tax relief, but did not identify a particular exemption or tax proceeding. The Board of Control for Cricket in India has recently stated that it does not enjoy a blanket exemption from income tax.
At the BCCI’s 95th Annual General Meeting in Mumbai on September 18, the board informed its members that it pays around ₹3,000 crore annually in income tax. BCCI secretary Devajit Saikia subsequently said the organisation was financially self-sufficient and did not receive government grants. Contemporary reporting on the AGM also specifically noted that the board does not have a blanket tax exemption.
Tax treatment involving cricket bodies can also vary depending on the entity, income involved and legal provisions being invoked. Cricket associations have separately litigated claims for charitable or other tax exemptions before courts and tax tribunals. That is different from treating the BCCI as entirely exempt from taxation.
Goenka’s intervention is therefore best understood as a policy comparison rather than a description of the BCCI as tax-free. His central argument is that research should receive stronger fiscal support because lower input costs could allow laboratories to spend more directly on experimentation, technology development and scientific capacity.
The issue places the focus on whether India’s tax framework should treat research equipment and software differently because they are inputs into scientific and technological development. The country already provides targeted relief for some research services and tax incentives for scientific expenditure, while the earlier broad 5 per cent GST concession for publicly funded research equipment was withdrawn in 2022.
Goenka’s proposal would go considerably further by removing GST from essential research inputs. Whether policymakers adopt such an approach would ultimately require decisions by the GST Council and governments on how to balance revenue considerations with the objective of lowering the cost of research and strengthening India’s domestic innovation ecosystem.
Follow for daily updates on cybercrime, corporate fraud, DFIR, hacking, investigations, and digital forensics
