
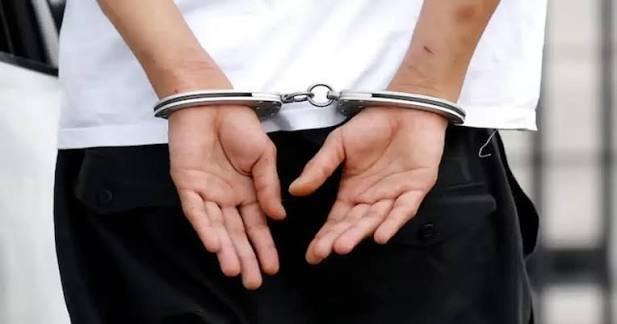

Delhi Police have arrested two men for allegedly posing as loan agents and cheating a Shahdara resident of ₹15 lakh after convincing him to send signed cheques for processing a low-interest loan and overdraft facility.
The accused have been identified as Adeeb Khan, 36, who police describe as the alleged mastermind, and Aneesh Ali, who allegedly provided a mule bank account and helped withdraw the money. Police recovered ₹6.95 lakh in cash from the two men.
A third alleged associate, identified as Rajendra, remains absconding.
Proposal for Conducting Cyber Crisis Drill, Tabletop Exercise (TTEx) & CCMP Readiness Exercise
Victim was looking for a loan and overdraft facility
The case began when Shahdara resident Akshay Verma was looking for an overdraft or loan facility.
Police say he came into contact with Khan, who presented himself as a Direct Selling Agent associated with Bajaj Finserv and other private banks and offered to arrange finance at an attractive interest rate.
A DSA is an independent or third-party intermediary who helps banks and financial institutions find customers and process loan applications.
Because legitimate DSAs are commonly used in India’s lending market, someone with prior experience in the industry can appear credible to a borrower.
Police allege that Khan exploited precisely that familiarity.
Three cheques sent without any face-to-face meeting
After gaining the victim’s confidence, Khan allegedly asked him to send three cheques and other documents required for processing the loan.
The cheques were sent through a delivery service to KM Trade Towers in Kaushambi.
Among them was a signed blank cheque for ₹15 lakh.
Police say the victim never met Khan in person before sending the documents.
The blank cheque was then allegedly misused rather than submitted as part of any genuine loan-processing procedure.
Investigators say the full ₹15 lakh was deposited into a private bank account being used as a mule account.
₹15 lakh withdrawn using two cheques
Once the money reached the mule account, police allege that it was withdrawn through two separate cheques.
A mule account is a bank account used to receive or move money on behalf of another person, often to make the financial trail more difficult to follow.
Investigators traced the account as part of the inquiry and examined transaction and withdrawal records to identify the people involved.
Police say the stolen ₹15 lakh was divided among the alleged participants.
Khan allegedly received ₹9 lakh, while Ali and the absconding Rajendra allegedly received ₹3 lakh each.
These remain police allegations and have not been proved in court.
₹6.95 lakh recovered in cash
Delhi Police said they recovered ₹6.95 lakh from the arrested accused.
The amount consisted of 1,390 notes of ₹500 denomination.
Investigators are now trying to recover the remaining money and establish whether part of the fraud proceeds was transferred elsewhere or spent before the arrests.
Police are also searching for Rajendra.
Khan and Ali were traced and apprehended on September 25 after investigators analysed financial and technical evidence connected to the case.
Phone, banking and internet records helped identify accused
The cybercrime team examined a wide range of digital and financial records.
These reportedly included the mule account, mobile numbers, IMEI and IMSI information, call-detail records, IP records, chats and the complete withdrawal trail.
IMEI is an identifier associated with a mobile handset, while IMSI identifies a subscriber on a mobile network.
When combined with bank records, call logs and internet information, such data can help investigators determine which devices and users were connected to suspicious transactions.
Police said continuous technical surveillance and field investigation eventually led them to Khan and Ali.
Alleged mastermind had previously worked as a real DSA
One of the most important details in the investigation is Khan’s professional background.
Police say he had previously worked as a DSA for several private banks and was also working as a third-party DSA on commission with a private bank.
That experience allegedly gave him knowledge of how genuine loan and overdraft processes operate.
Police say he used his professional contacts and access to customer information to identify people who were actively looking for finance.
He would then allegedly contact potential victims through messaging applications, present himself as a genuine loan intermediary and offer loans or overdraft facilities at attractive rates.
After gaining their trust, he allegedly obtained cheques and documents under the pretext of processing applications.
Why blank cheques create a major fraud risk
The case highlights a simple but serious financial risk.
A signed blank cheque gives the holder considerable control over how the cheque is ultimately filled in and presented.
Borrowers may sometimes believe a blank cheque is required as security or for processing, particularly when dealing with someone who appears connected to a bank.
But consumers should independently verify any such requirement with the lender through its official customer-care channel or branch.
A genuine-looking agent, professional terminology or knowledge of banking products is not proof that a transaction is authorised by the bank.
Police checking for more victims
The investigation has not ended with the two arrests.
Police are examining whether the accused used the same method to target other borrowers and whether additional mule accounts were involved.
Investigators are also looking for other associates who may have helped collect documents, receive funds or withdraw money.
The allegation against Khan is particularly significant because police believe his earlier experience in legitimate loan distribution may have helped him make the fraud appear genuine.
The accused remain entitled to contest the allegations, and the case will have to be established through evidence and court proceedings.
What this means for you: Never hand over a signed blank cheque to a loan agent without independently confirming the requirement with the bank or financial institution. Verify any DSA through the lender’s official channels and avoid sending cheques or sensitive financial documents to people you have never met.
Follow for daily updates on cybercrime, corporate fraud, DFIR, hacking, investigations, and digital forensics
