
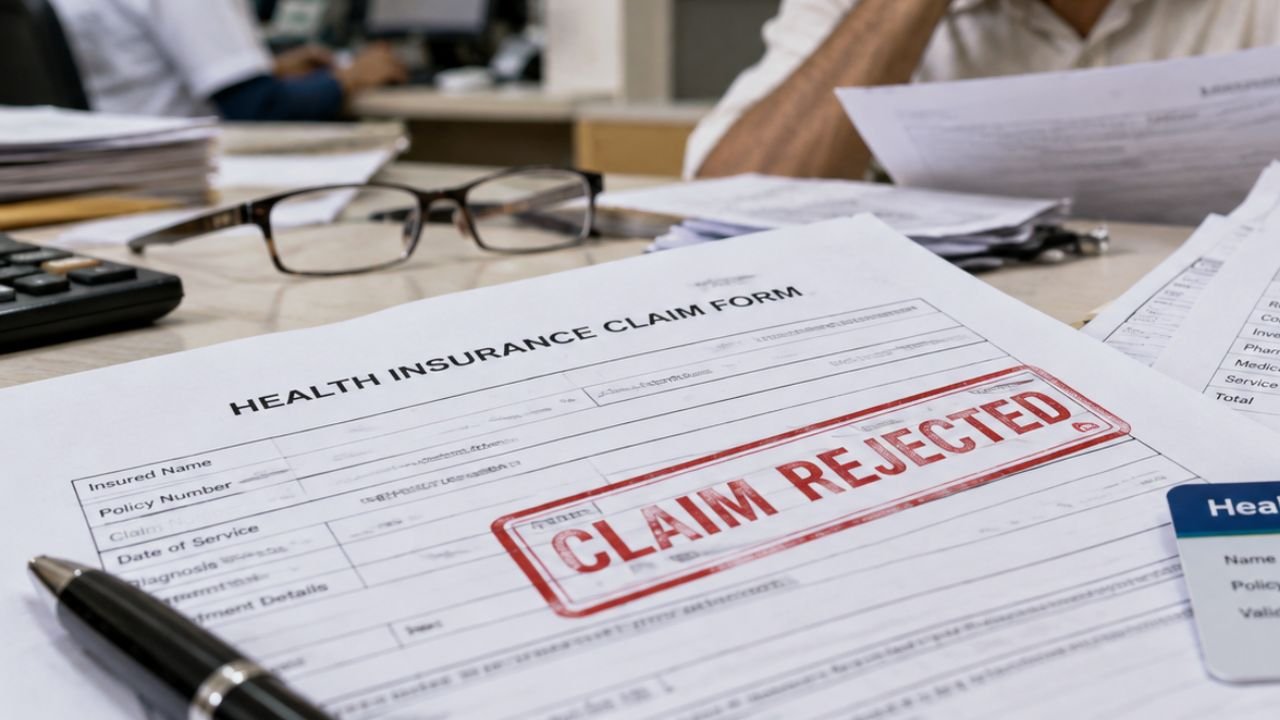
New Delhi. For health insurance policyholders, the rejection of a claim can become a major concern at a time when they are already dealing with the financial burden of medical treatment. In several cases, insurers have denied payments citing alleged violations of policy conditions, concealment of illnesses or smoking habits. In particular, some complaints have involved policyholders being described as ‘chronic smokers’ and having their claims rejected on that basis. Such cases have raised questions over whether insurers have adequate medical records and documentary evidence to establish such allegations.
During the financial year 2024-25, 29.51 lakh health insurance claims were rejected. The claims involved an amount of around ₹11,412 crore. Available data indicates that nearly eight out of every 100 health insurance claims were rejected. Reasons cited in claim disputes have included alleged violations of policy conditions, concealment of medical conditions and disputes over smoking habits.
Proposal for Conducting Cyber Crisis Drill, Tabletop Exercise (TTEx) & CCMP Readiness Exercise
Under insurance regulations, a claim cannot be rejected merely on the basis of suspicion or oral information. The insurer is required to provide the policyholder with a clear reason for rejecting the claim and specify the relevant policy condition under which the claim has been denied. If smoking or concealment of a medical condition is cited as the basis for rejection, the records and documents supporting the insurer’s position become important.
A similar case came before the Coimbatore District Consumer Disputes Redressal Commission. A health insurance claim worth around ₹10.15 lakh related to treatment for an aneurysm was rejected by the insurer, allegedly on the ground that the policyholder was a long-term smoker. The policyholder argued that the company did not have solid evidence to establish long-term smoking. The consumer commission ordered the insurer to pay around ₹10.15 lakh towards the health insurance claim.
In another case from Hyderabad, a 67-year-old policyholder’s claim was allegedly rejected on the ground that the person had concealed a history of high blood pressure. During proceedings before the consumer commission, the insurer reportedly failed to produce a supporting document establishing the allegation. Such cases have raised questions about whether an insurance payment can be denied merely on the basis of assumptions about a person’s medical history or habits.
Under the applicable rules, insurers are required to process claims in accordance with the terms and conditions of the policy and relevant regulatory provisions. If a claim is rejected, the insurer must provide a specific reason for the rejection and mention the relevant policy condition. The policyholder must also be provided with complete information about the grievance-redressal mechanism, including details of the insurer’s internal complaint process and the Insurance Ombudsman.
There are also prescribed timelines for claim settlement. Under normal circumstances, a claim is expected to be processed within 30 days. If an investigation is required, the insurer is required to initiate it promptly and complete it within a maximum period of 30 days. After receiving all necessary documents, the claim is required to be settled within 45 days.
Policyholders have also complained that insurers sometimes seek additional documents close to the deadline for processing a claim. This can result in delays in receiving payment after treatment and, in some cases, claims remaining pending for months. In such situations, policyholders are advised to obtain every request for additional documents and every decision from the insurer in writing.
If a claim is rejected by describing the policyholder as a ‘chronic smoker’, alleging concealment of an illness or citing a violation of policy conditions, the policyholder should examine the rejection letter carefully. The letter should state the specific reason, identify the relevant policy clause and explain the basis for the decision. Documents such as medical reports, previous treatment records and doctors’ records can become important if the dispute is challenged.
Health insurance is intended to provide financial protection against the high costs associated with illness and medical treatment. Therefore, when a claim is rejected, policyholders should not rely only on verbal explanations from the insurer. They should seek written reasons and supporting documents and check whether the cited policy condition actually applies to their case. This becomes particularly important in disputes involving alleged smoking habits or pre-existing medical conditions, where the insurer’s decision should be examined against the available medical and documentary records.
Follow for daily updates on cybercrime, corporate fraud, DFIR, hacking, investigations, and digital forensics
