
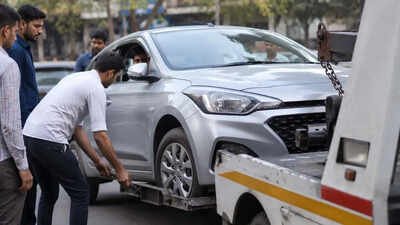
The Supreme Court has ruled that lenders cannot use force or coercive methods to repossess vehicles after loan defaults.
What brought the dispute before the Court?
The case arose from the repossession and subsequent sale of a commercial vehicle financed by Cholamandalam Investment and Finance Company Ltd. The borrower had defaulted on loan repayments on multiple occasions.
According to the borrower, unidentified persons broke the truck’s steering lock at about 1 a.m. on April 9, 2023, and took away the vehicle without serving prior notice. After the Allahabad High Court dismissed the borrower’s plea, the matter reached the Supreme Court.
The Court examined whether a financier’s contractual right to repossess a vehicle following default could be exercised in such a manner without adhering to fair recovery procedures.
Proposal for Conducting Cyber Crisis Drill, Tabletop Exercise (TTEx) & CCMP Readiness Exercise
What did the Supreme Court rule?
A bench comprising Justice P. S. Narasimha and Justice Alok Aradhe reiterated that financiers may have a contractual right to take possession of financed assets when borrowers default. However, that power must be exercised within the framework of law.
The Court held that contractual rights cannot extend to the use of force or coercive methods for loan recovery. It emphasised that lenders must follow lawful procedures while exercising their recovery rights.
The ruling addressed the balance between a lender’s need for an effective recovery mechanism and a borrower’s entitlement to fair treatment, notice and due process before losing possession of an asset.
What do RBI guidelines require?
The Court referred to the Reserve Bank of India’s Fair Practices Code for Lenders guidelines issued on May 5, 2003. These require lenders to avoid undue harassment of borrowers and specifically prohibit the use of muscle power for loan recovery.
The bench also relied on the Supreme Court’s earlier decision in Manager, ICICI Bank Ltd. v. Prakash Kaur and Others, dated February 26, 2007. That ruling had stressed that loan recovery and vehicle seizure must be undertaken through lawful means and that banks cannot employ force to obtain possession.
Why was the loan agreement questioned?
In the present case, the Court found that the loan agreement gave the financier substantial unilateral discretion over whether notice was required and over the manner and timing of the vehicle’s sale.
The Court held that such an arrangement was inconsistent with RBI guidelines and provisions of the Indian Contract Act, 1872. It further noted that the borrower had not received the required seven-day notice before repossession. Taking possession after breaking open the steering lock, the Court observed, bore the characteristics of coercive recovery practices previously condemned by the Supreme Court and the RBI.
What directions did the Court issue?
The Supreme Court ordered payment of compensation to Sharma for violation of his constitutional rights. The amount of compensation is not stated in the material available. The Court also directed the Reserve Bank of India to take effective steps to ensure genuine compliance with its guidelines and circulars governing recovery practices.
The judgment underlined that a lender’s legitimate interest in recovering unpaid loans must operate alongside the borrower’s right to notice, fair treatment and due process, particularly where repossession involves an asset used to earn a livelihood.
Follow for daily updates on cybercrime, corporate fraud, DFIR, hacking, investigations, and digital forensics
