Follow us on Google News

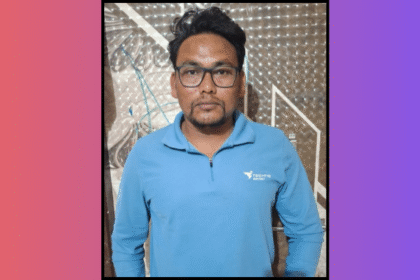
In a significant breakthrough in a ₹78 lakh online investment fraud case, cyber crime investigators have arrested a Virar-based businessman for allowing international cyber fraudsters to use his commercial bank account to launder scam proceeds.
Authorities established that the account was integrated into a massive distributed network, surfacing across multiple cyber fraud complaints registered across several Indian states. Preliminary findings suggest that crores of rupees siphoned from victims were routed through this single node before being dispersed to other beneficiaries, with components of the money trail extending overseas.
The arrested accused has been identified as Nilesh Upadhyay, a 38-year-old tour and cargo operator. Investigators allege that he permitted cyber criminals to operate his banking framework in exchange for a fixed commission cut. The specific account was weaponized by a fraud cartel that cheated a 65-year-old retired resident of Bhandup out of ₹78 lakh through a fake online trading scheme.
https://the420.in/future-crime-summit-2026-registrations-open-new-delhi-tech-enabled-crime/
The WhatsApp Investment Grooming
According to the initial investigation, the victim was added to an unauthorized WhatsApp group where individuals posing as elite investment advisors regularly shared stock market tips, technical trading strategies, and screenshots of purported high-margin profits. The fraudsters convinced the retiree to download a fraudulent mobile trading application, initially displaying completely fabricated gains to build trust and encourage deep capital investments.
Believing the digital interface to be genuine, the victim invested substantial savings across multiple transactions. However, when he later attempted to withdraw his principal capital and accrued profits, he discovered that the platform blocked all withdrawal requests. Realising he had been systematically deceived, he approached cyber crime authorities and lodged a formal complaint.
National Mule Registry Traces
During the digital financial probe, investigators traced the movement of funds and found that an immediate installment of ₹50,000 from the defrauded amount had been transferred directly to a bank account linked to Upadhyay’s travel business. This discovery prompted a deep audit of the account’s operational ledger.
Further analysis through the National Cyber Crime Reporting Portal (NCRP) revealed that the exact same account had surfaced in multiple active cyber crime complaints registered in Maharashtra, Gujarat, Telangana, Karnataka, and West Bengal. Investigators confirmed this pattern indicates the business setup was functioning purely as a “mule account” to receive and redistribute funds generated through multi-state scams.
Operational Logistics and Commission Framework
According to investigators, Upadhyay surrendered absolute control of his banking infrastructure by handing over the account’s physical cheque book, ATM card, linked SIM card, and internet banking credentials to syndicate associates based in Lucknow, Uttar Pradesh. In return, he received a commission ranging between 5 and 10 per cent on all high-velocity transactions routed through the account.
Renowned cyber and financial crime expert and former IPS officer Prof. Triveni Singh said the use of proxy business accounts has become a primary tactical pillar for organized cyber syndicates. Fraudsters routinely lure individuals with the promise of easy commissions, persuading them to surrender control of their bank accounts to layer transactions and obscure the origin of illegally acquired funds.
He cautioned that sharing banking credentials, ATM cards, SIM cards, or account access with third parties exposes individuals to severe legal consequences under anti-money laundering and information technology statutes, regardless of direct participation in the front-end scam.